Our research
Access all our publications and columns. Use the filters to easily find what content you are looking for.
Filters
All publications
276 results
Top of Mind - AI and the neutral rate: Live and let rise
- Macro economy
-
Where policy rates settle in the long run, and where long-term yields trade, depends on the real neutral rate of interest, r*. AI is now putting upward pressure on it from two sides. The build-out of data centres, chips and power is the largest investment boom in decades, and the productivity gains it promises could change how fast the economy grows. This note asks what both do to r*, in the US and the euro area.
Lagarde set to hike again before her departure
- Macro economy
-
Top of Mind - AI capex boom to die another day
- Macro economy
-
A troika of capex booms – AI, defence and clean energy – is set to reach USD 3.5 trillion this year across the US, Europe and China. The main growth impulse is coming from AI capex, which is growing rapidly, but signs are that the pace will slow in 2027. If AI capex is in line with guidance, the growth impulse will not fall off too much and will be more than offset by higher US defence investment. US capex will therefore remain strong but the spillovers to other economies will likely be less, while EU and China capex will slow. We do not expect an AI capex bust in the near term, but the economics do not bode well for the medium term: It will probably die another day.
Top of Mind - Optimism and worry in Bangkok
- Macro economy
-
I spent the last week at the Annual Meetings of the IMF and World Bank in Bangkok attending a wide variety of meetings. The ability of the global economy to withstand shocks was a key theme of the meetings, and most expected this to continue. Worries about the risks remained, from the sustainability of the AI capex cycle, to geopolitics, rising interest rates and sovereign debt. AI capex would remain strong, but there was a general agreement that the scale of capex did not justify the revenues that would be generated. Although flagged as a risk, geopolitics may now be an underrated one and turn out to be ‘the boy who cried wolf’. Most saw the rise in bond yields as being the markets re-evaluating r* but there was lively debate on this topic. France was seen as the major sovereign risk, though the degree of concern varied, while it was agreed that interventions were unlikely.
Global Monthly - Will the bond sell-off derail the economy?
- Macro economy
-
The global economy has shrugged off repeated shocks, but rising bond yields are emerging as a new challenge to the expansion. Bond markets are mostly pricing higher neutral rates, with fiscal concerns adding to yield increases in France, Belgium and the UK. Higher rates may slow the expansion, but they are unlikely to derail the US or eurozone economies on their own. The growth impact will be bigger in fiscally vulnerable economies, with France facing the twin challenge of consolidation and bigger rate rises. Markets may be overestimating how long policy rates will stay elevated, leaving room for bond yields to fall back next year. Regional updates: Rising yields temper rate hike pace in the Eurozone. We raise our growth forecast in the Netherlands following a strong H1. In the US, narrower inflation reduces the urgency of the Fed to hike. Growth gains momentum in China helped by targeted fiscal support
Updating our scenario: Higher for longer
- Macro economy
-
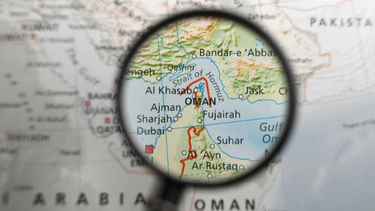
The recent escalation in the Middle East likely means higher for longer energy prices, inflation and interest rates. Energy supply through both Hormuz and the Saudi East-West pipeline is likely to remain constrained in the coming months. The higher profile for energy prices leads to an upward revision to our inflation forecasts, with a longer period of above-target rates. Economic growth remains resilient near term; will be dampened next year on higher energy prices, interest rates and slower AI capex growth. Faced with a longer period of above-target inflation, central banks are likely to move monetary policy into moderately restrictive territory. We expect 50bp of rate hikes from both the Fed and the ECB before year end, while the door could open for rate cuts by the end of next year. Bond yields are seen heading lower over our horizon as there are more hikes priced in than we expect in our new base case. Rising term premia should drive curve steepening.
ECB Watch - ECB rate hike cycle looks far from over
- Macro economy
-

Global Monthly - Deal or no deal: Does it still matter?
- Macro economy
-
The energy shock is back, but its impact more idiosyncratic than before. A lot of energy is getting through Hormuz ‘dark’, and this lowers the importance of a deal to re-open the Strait. Less important ≠ not important, and a deal would still help restore LNG flows, lower inflation and reduce European energy supply risks. Resurgent energy prices and stubborn inflation are keeping central banks on edge. Markets have probably gone too far pricing hikes…but the risk of more tightening than we currently expect has risen.
Top of Mind - Rising US Treasury yields Q&A
- Macro economy
-
Rising US Treasury yields have been top of mind recently and we have had many client questions on what is driving the market, potential policy interventions and the overall outlook for long-term interest rates. Below, we tackle these issues in a short Q&A format.
Labour market weakness could re-balance Fed concerns
- Macro economy
-