Our research
Access all our publications and columns. Use the filters to easily find what content you are looking for.
Filters
All publications
30 results
Japan - The BoJ carries on
- Macro economy
-
Q2 GDP and monthly data point to strengthening growth momentum, …although risks stem from larger and longer energy shocks, rising interest rates, frictions with China and a potential slowing of the AI boom. Inflation driven up by energy shock, AI boom, and stronger wage growth. Regime shift 1: Rate hike path BoJ (we expect another hike tomorrow) and QT (although moderated) a key factor pushing up bond yields… Regime shift 2: … and so is PM Takaichi’s more expansive fiscal stance. JGB yields continued to increase, as the curve bear flattened in recent months. Lower hedging costs will only provide a small relief for OATs. Joint FX intervention countered yen weakness… but a structural shift in rate spreads and investor behaviour crucial for further yen recovery.. We expect sideways movement in the yen in the coming months and a further recovery towards the end of 2027.
Prinsjesdag 2026: A budget in search of a majority
- Macro economy
-
The Minority cabinet Jetten I presented its first full budget today at ‘Prinsjesdag’ (Budget Day). Today’s budget is yet without a majority and therefore features policies aimed at securing support from opposition parties. As a result, changes to today’s budget are expected during the upcoming budget debates. The impact on the budget deficit is expected to be limited, given tight agreement among coalition partners on budget rules… and as a result, we do not expect a significant impact on the funding need for 2027. The Dutch economy is resilient while long term challenges are mounting and inflation stays too high compared to peers.
Updating our scenario: Higher for longer
- Macro economy
-
The recent escalation in the Middle East likely means higher for longer energy prices, inflation and interest rates. Energy supply through both Hormuz and the Saudi East-West pipeline is likely to remain constrained in the coming months. The higher profile for energy prices leads to an upward revision to our inflation forecasts, with a longer period of above-target rates. Economic growth remains resilient near term; will be dampened next year on higher energy prices, interest rates and slower AI capex growth. Faced with a longer period of above-target inflation, central banks are likely to move monetary policy into moderately restrictive territory. We expect 50bp of rate hikes from both the Fed and the ECB before year end, while the door could open for rate cuts by the end of next year. Bond yields are seen heading lower over our horizon as there are more hikes priced in than we expect in our new base case. Rising term premia should drive curve steepening.
Transaction Trends - The pension transition - More pension, more spending?
- Macro economy
-
This year, approximately 1.5 million Dutch retirees are noticing the effects of the pension transition in their wallets. Based on anonymized transaction data, we analyze the spending impulse resulting from the “conversion bonus” (invaarbonus), the additional pension indexation due to the transition to the new pension system. Retirees spend on average only 22% of an extra euro of pension income. This percentage declines at higher ages. Retirees with lower incomes or limited financial buffers tend to spend a larger share of the additional income. Despite the relatively small percentage effects, the size of the conversion bonus, combined with a large number of elderly people, still provides a modest boost to the Dutch economy.
Dutch cabinet ambitious but dependent on opposition
- Macro economy
-
• D66, VVD and CDA are forming a Dutch minority cabinet lacking a majority in both parliament and the senate, policy making will remain a challenge and dependent upon opposition buy-in • The coalition agreement seeks to rebalance consumption and investment spending, in favour of the latter. For instance more will be spent on defence and housing, at the cost of healthcare and social security • The agreement limits the budget deficit at 2% of GDP, perhaps also to leave room for opposition wishes. • This cabinet is shifting towards a more constructive stance towards Europe • The Netherlands will be put back on track to meet the EU Climate Law targets, with likely strong opposition support
Dutch elections - Convergence in polls suggest a tight race
- Macro economy
-
The Dutch head to the ballot box coming Wednesday, polls suggest that support for the four largest parties has converged. A centrist 4-party coalition now could have a majority, but is being ruled out for now by the centre-right VVD party-leader Yeşilgöz. Such a coalition has overlap but also large differences, suggesting a challenging formation process lies ahead. The election programme of each of the parties points to higher deficits in the coming years... but for next year, we expect the impact on the funding need to be limited because the policy changes will take time to have an effect. Unlike two years ago, the pension transition is not on the political agenda during these elections.
Dutch elections - Consensus for high deficits
- Macro economy
-
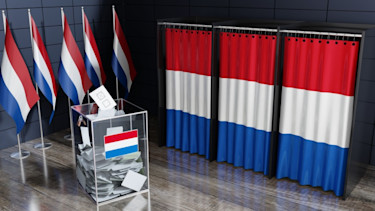
The Dutch head to the ballot box on the 29th of October in an important election after a period of political turmoil. Polls signal quite some shifts, with far-right PVV as election winner once again, though it is deemed unlikely they will enter a new coalition. While still very uncertain, with centre parties, such as the CDA, winning, a more centrist government looks increasingly feasible. Party programmes share a consensus for large deficits, putting longer term public finances under pressure. Chances of a coalition with a more constructive stance towards the EU and traditionally sensitive issues, such as joint financing, have increased.
Dutch budget day overshadowed by upcoming elections
- Macro economy
-
Little surprises on what was and wasn’t in yesterday's budget
Japan - The Land of the Rising Yields
- Macro economy
-
We expect drags from US tariffs to keep a lid on Japanese growth. Trade talks with the US are taking quite some time. The Bank of Japan (BoJ) recently lowered its inflation forecasts, but upside risks remain. We expect the BoJ to stay on a cautious, gradual hiking path. In its June meeting, the BoJ announced to slow its pace of tapering, as expected. High public debt and rising rates pose challenges, but there are risk-mitigating factors. Meanwhile, the Japanese government bond curve has steepened due to a higher term premium. We do not have indications for structural US debt outflows by Japanese investors, yet. We expect the yen to appreciate versus the US dollar in 2025-2026.
Dutch Macro Perspectives - Wilders blows up coalition amid elevated uncertainty
- Macro economy
-
Dutch government falls as the far-right PVV quits the coalition. The current government assumes caretaker status, meaning they only govern on selected topics. While uncertain at this stage, new elections are likely to be held, possibly in October.