Energy Strategist - Energy markets remain tight

Energy markets remain under pressure despite recent policy interventions and efforts to boost supply. While coordinated releases of strategic reserves and the rerouting of energy flows have provided some relief, low inventories, ongoing geopolitical uncertainty, and constrained infrastructure continue to leave oil, gas, and refined product markets vulnerable to further disruptions. The following highlights the key developments across these markets.
Oil markets
The coordinated G7-IEA release of 100 million barrels has eased oil prices only slightly, because it largely reflected prior commitments
The oil market remains tight, as shown by the high premium for immediate delivery (including high transportation costs)
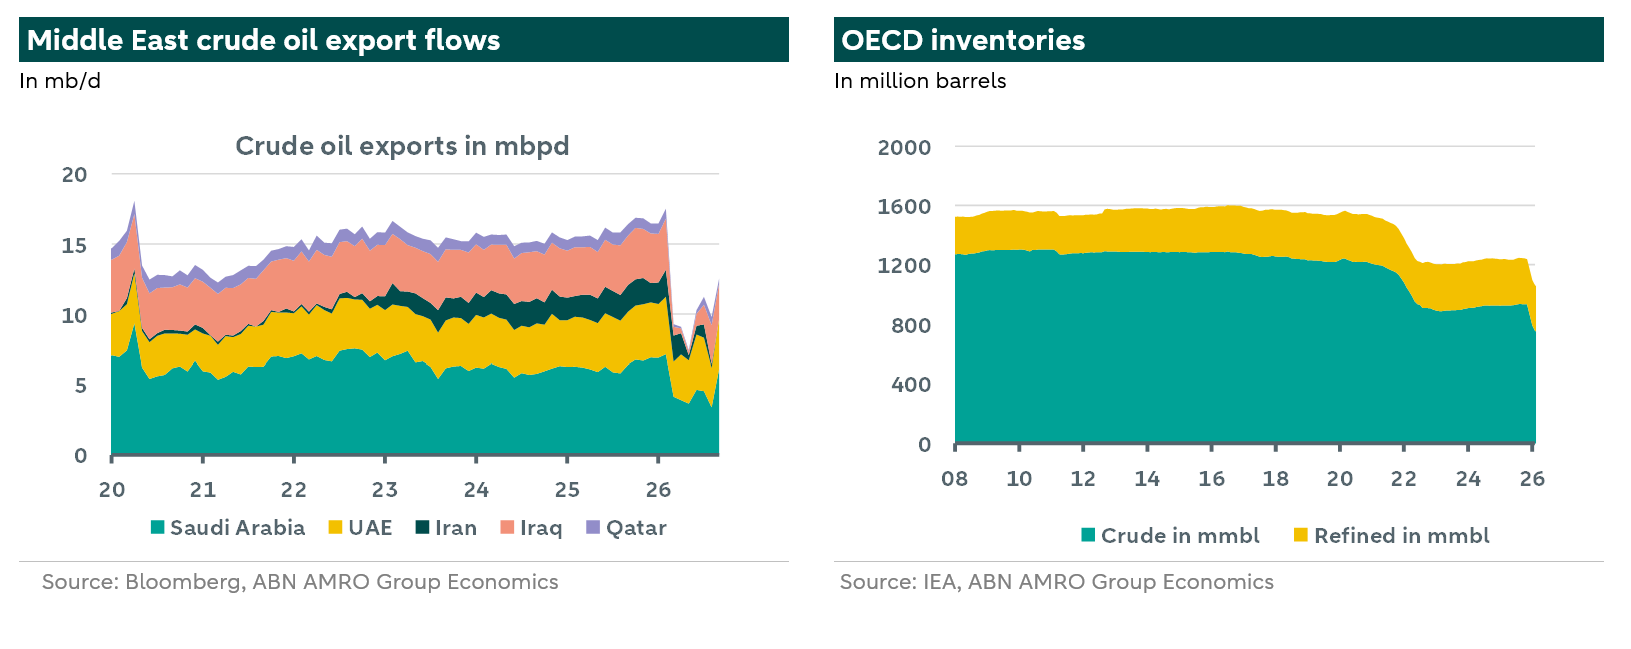
Middle Eastern exporters are restoring flows through alternative routes and shipping methods, bringing exports back close to pre-conflict levels
However, low inventories and continued uncertainty are keeping the market sensitive to further disruptions
Gas markets
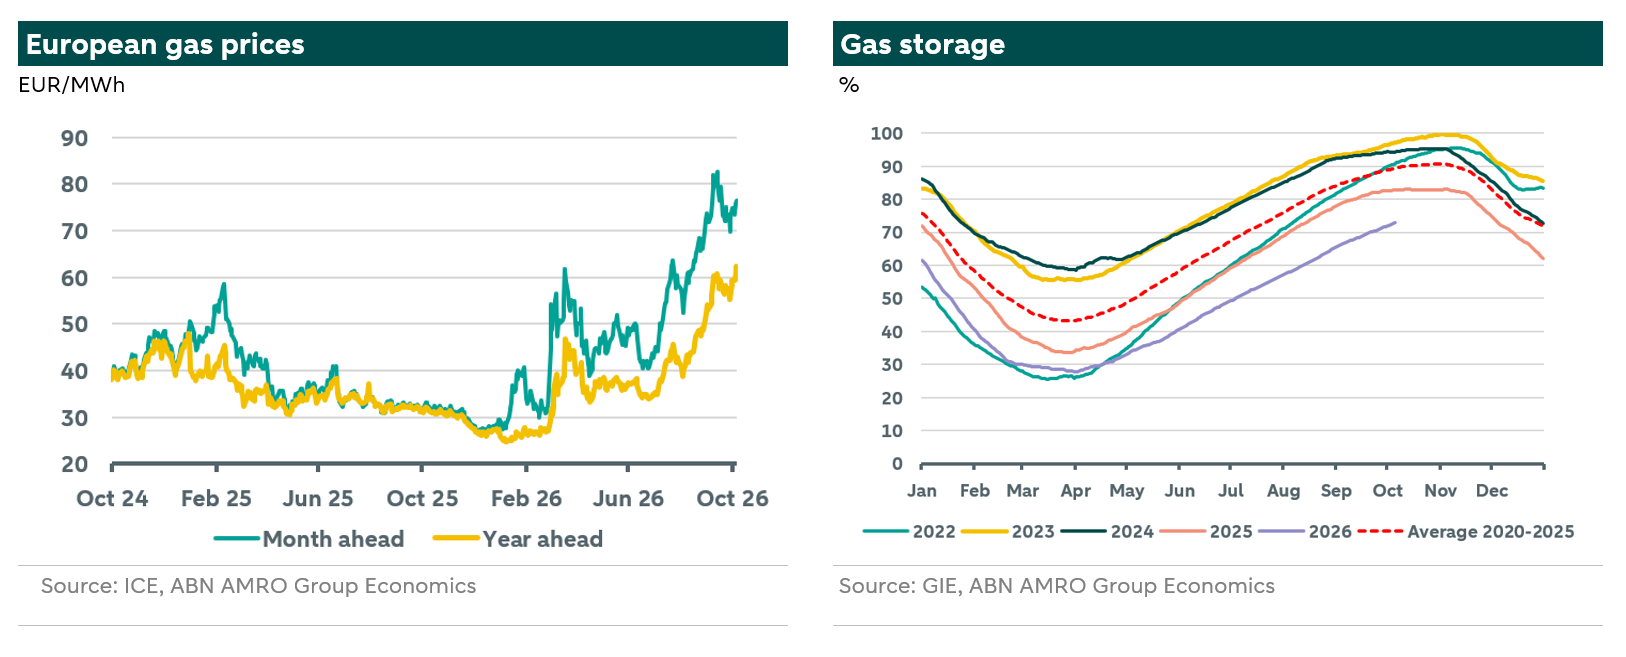
European gas storage is expected to reach around 78% by November, well below the 90% target
Under normal winter conditions, storage could fall to about 24% by the end of March; a severe winter could reduce it to a critical 10-15%
Alternative supplies and weaker demand - particularly from price-sensitive Asian buyers - can partly offset disruptions to Qatari LNG
However, Europe still lacks a sufficient operational buffer, leaving the market vulnerable to weather and supply shocks
Refined product markets
The G7 announcement has lowered refined product prices and refinery margins
Tight crude supply, low inventories, high transport costs and strong demand will keep prices elevated
Refinery disruptions across Russia, the Middle East, Asia and Europe are limiting output
Global refinery throughput is unlikely to recover to pre-conflict levels this year
Oil markets
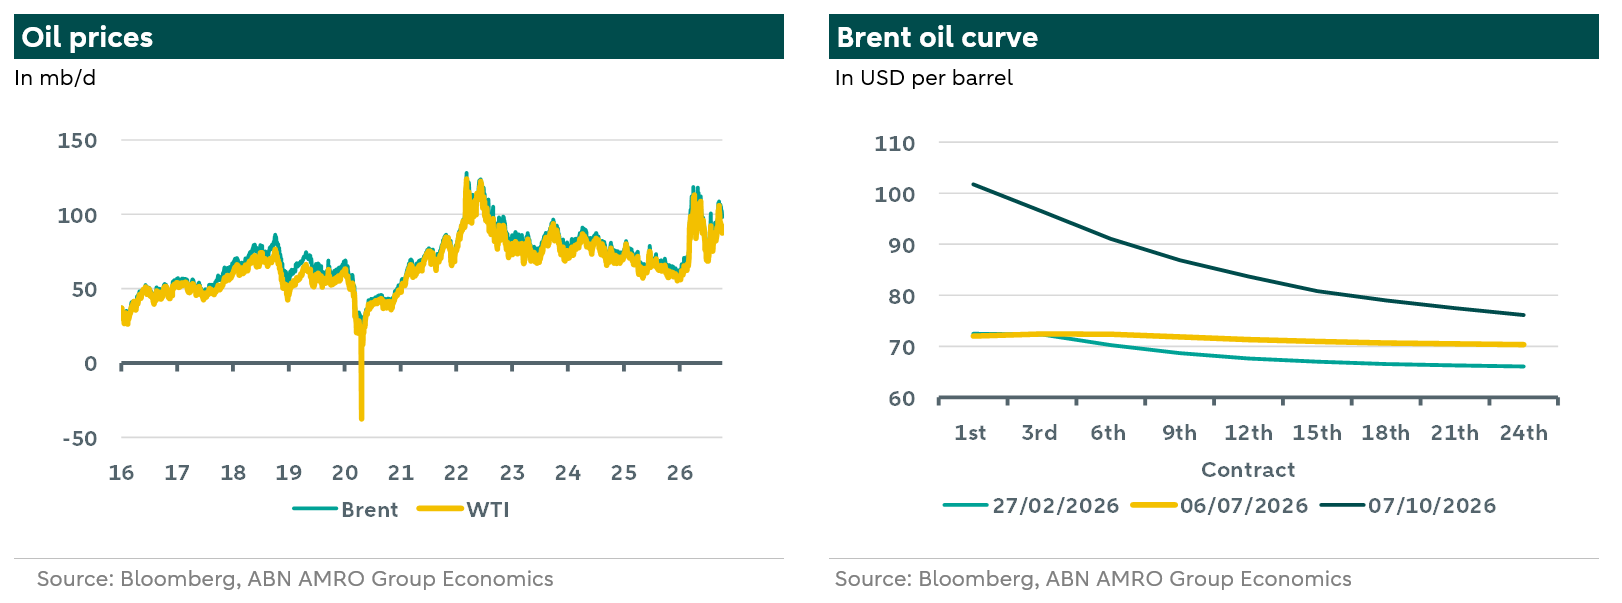
On 2 October, the G7 countries agreed to coordinate the release of 100 million barrels of crude oil and fuel through the IEA over four months. This includes a substantial release of diesel during the first 20 days. However, most of the 100 million barrels are expected to come from earlier commitments rather than represent additional supply. Oil prices have therefore fallen slightly (see the chart below on the left), but the market remains tight. The futures curve (see the chart below on the right) shows that oil for delivery in the coming months is still priced well above oil for later delivery. Based on dated Brent prices for immediate delivery, the refinery margin is currently -44 after all costs are included. This is the lowest level since 15 April. However, refinery margins remain high for future delivery.
Middle Eastern countries continue to use alternative export routes. These include pipelines through Yanbu, Fujairah, Kirkuk-Ceyhan and SUMED, as well as dark transits and ship-to-ship transfers. During a dark transit, a tanker crosses the Strait with its automatic identification system switched off. In a ship-to-ship transfer, crude oil is loaded onto a smaller tanker inside the Gulf. The tanker then passes through the Strait without transmitting its location and transfers the oil to a larger vessel outside the Strait. Saudi Arabia has restored its Gulf exports and Red Sea capacity.
The latest data show a strong recovery in Middle Eastern crude oil exports, in line with weekly trade-flow figures. Exports from Saudi Arabia, the UAE, Iran, Iraq and Qatar have reached about 80% of their average pre-war level. They currently total around 13 mbpd, compared with 16 mbpd before the conflict. To support exports, these countries have adopted different pricing strategies. Some offer buyers a discount for loading crude oil inside the Gulf to compensate for higher costs and uncertainty. Others quote the crude oil price separately and charge an additional fee for delivery outside the Strait of Hormuz, while some offer both options. In short, the oil market is finding ways to move crude oil out of the Gulf despite the disruption around the Strait of Hormuz. A few months ago, export data this strong would probably have pushed oil prices much lower. However, inventories are now considerably lower and conditions remain uncertain. The market had previously moved quickly to price in oversupply for next year. It is now more aware that conditions can change rapidly, supply constraints are likely to persist and inventories remain very low.
Gas markets
Europe entered October with gas storage heading towards 73%. The mild weather and stable flows from the US so far help speeding up the injection rate. Meanwhile, flows from Norway are down this period due to planned seasonal maintenance. At this rate, we see storage reaching 78% by November, far from the 90% target between October and December, assuming favourable weather conditions (no major cold spells or long periods of slow wind), and no unexpected disruptions from the US or Norway in the meantime. We anticipate the coming winter to be an average one in term of temperature, with 24% of storage left by the end of March. In case of a difficult cold winter, we could reach 10-15%, a very critical and challenging level for the following injection season.
Still, storage is only one aspect that helps Europe traverse the winter safely. Storage represents only 25-30% of European winter consumption. The rest relies mainly on the continuation of flows during winter, especially from the US and Norway. US LNG export facilities are located in a hurricane active area, which make disruptions more probable. Similarly for Norway, any unplanned outages would land heavy on prices. Not to forget, the continuous competition from Asia on spot cargos which will keep prices elevated. Europe does not face a direct severe shortage in flows but misses a sufficient operational buffer.
All in all, alternative supply and lower demand (mainly from price sensitive Asia) can offset part of the disruption of Qatari LNG but not restore a comfortable operational buffer for Europe yet. Europe will have to navigate the coming winter on thin ice. That is, Europe can probably secure enough gas, but security of supply will come at a higher price and with lower resilience. Any one or simultaneous weather or supply shocks would induce strong price hikes during the heating season, and of course higher for longer prices that increase households' energy bill and keep inflation and interest afloat.
Going into 2027 several factors come into play. Europe’s ban on Russian LNG comes into force, while more LNG capacity additions are planned to come online. For non-Qatari LNG new additions, we anticipate an increase in LNG supply mainly from the US. For example, in the first half of 2027, both train 2 and 3 are planned to become fully operational in the Golden Pass facility. Rio Grande LNG and Port Arthur LNG are also important US additions. Also, additional capacity in Canada (LNG Canada phase 1) is expected to add another significant liquification capacity. Finally, Europe may switch to a stricter policy response to enhance its resilience to energy shocks, as storage targets regulation expires in 2027. Strategic reserves are one policy option on the table, where European states play a greater role in securing supplies and managing storage.
Refined products markets
The G7 countries agreed to front-loaded release for diesel. This would be possible, although in low volumes, while no EU nation explicitly committed to do so within a 20-day window. All in all, this allows Europe to draw on its inventories rather than compete for US diesel exports. As a result, diesel and other refined product prices, as well as refinery margins, have declined somewhat (see the chart below on the left).
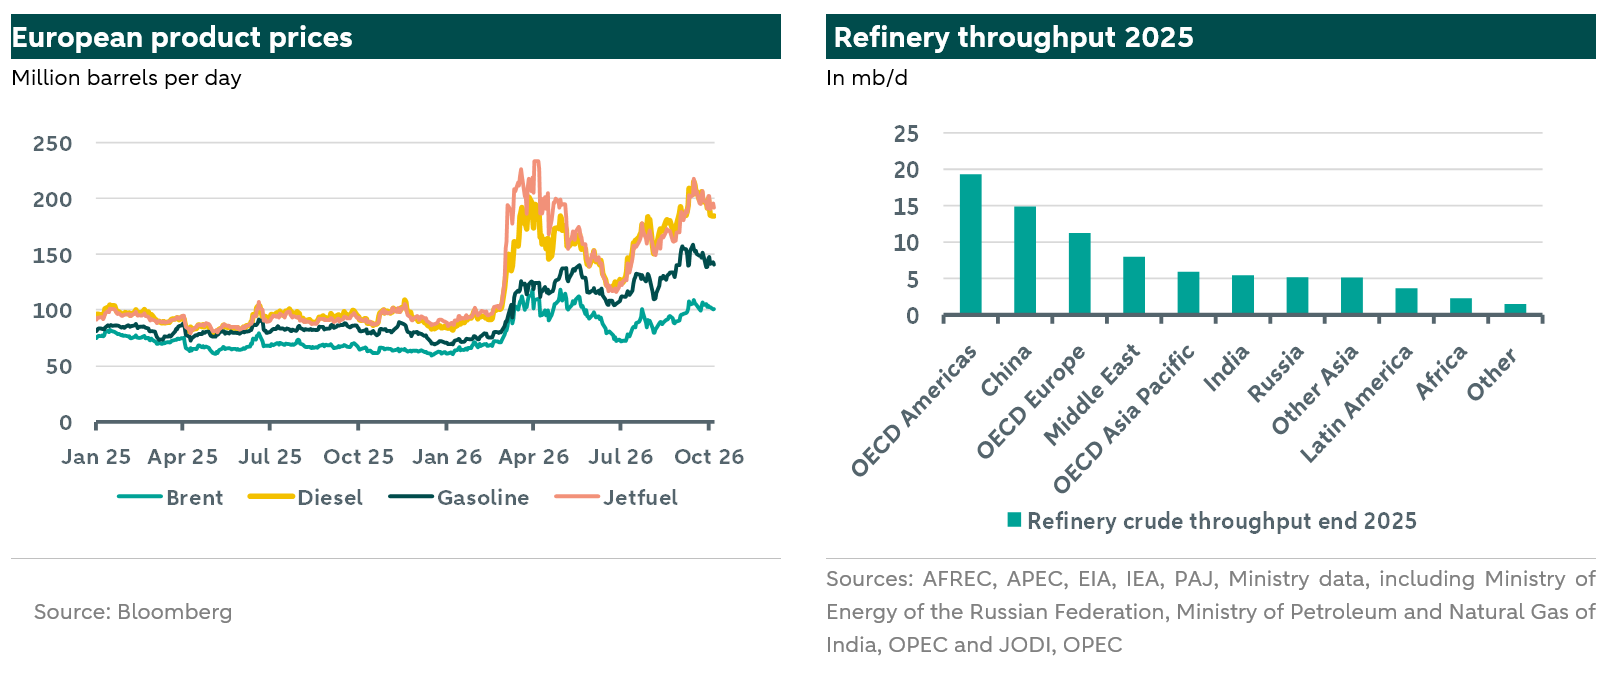
We expect refined product prices to remain high because the market faces several pressures simultaneously: tight crude oil supply, reduced refinery capacity, stronger demand in the fourth quarter, higher transport costs and low inventories. These conditions have already pushed refinery margins significantly higher.
We expect the crude oil market to remain undersupplied this year, which should continue to support refined product prices. Global refinery capacity is constrained by several disruptions. Ukrainian attacks have damaged Russian refineries, drone strikes have reduced capacity in the Middle East, and the closure of the Strait of Hormuz has disrupted the supply and transport of both crude oil and refined products. In Asia, some refinery capacity has been shut down because refiners have had limited access to crude oil following disruptions in the Strait of Hormuz and Chinese restrictions on product exports. China has effectively halted refined product exports for October. In Europe, refineries in Germany’s Rhineland have also reduced throughput because water levels in the Rhine have fallen to their lowest level since records began in 1880. These developments are reflected in lower refinery throughput.
Lower refinery throughput has pushed refinery margins and refined product prices higher. US refineries are already operating close to full capacity, leaving little scope to increase output. A US ban on diesel exports would have tightened the market further. As discussed above, market participants are finding ways to transport crude oil and refined products out of the Gulf. Even so, repairing damaged refineries in the Middle East will take time. If the Strait of Hormuz reopens, crude oil supply and logistics should improve, but repairs and maintenance at damaged facilities could continue until the end of the year. Russian refinery activity is also at a 24-year low, and a recovery is likely to take several months. We therefore do not expect refinery throughput to return to pre-conflict levels this year.
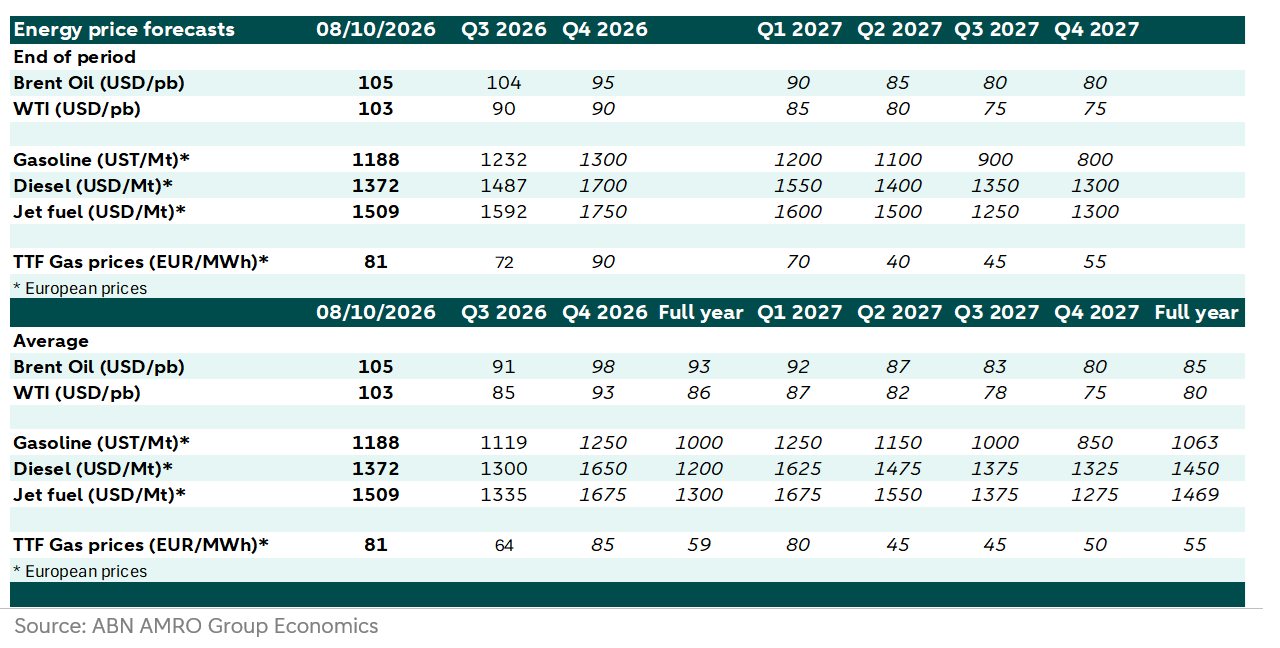
Our energy price forecasts